
Lifetime income
Legacy-changing outcome
Create income you can count on — and a legacy worth protecting — with this FIA industry first.
Take out the guesswork with a Lincoln fixed indexed annuity and its built-in income benefit, Lincoln ProtectedPay® Select1 — now with Estate LockSM, so you don't have to choose between lifetime income and a meaningful legacy. Here's a closer look at how it works.
Protected retirement savings and growth
- Grow future income by 10% each year2
- Capture upside potential for your account value
- Stay 100% protected from market losses
Protected lifetime income
- Count on income that will never go down
- Plan for certainty with lifetime income payments
- Add protection for a spouse
Protected legacy for loved ones
- Plan for both income and a meaningful legacy
- Leave beneficiaries the full purchase amount3
- Available for an additional cost of 0.45%
Click through each tab to see how it works in each phase of retirement.
- Protected savings and growth
- Protected lifetime income
- Protected legacy for loved ones
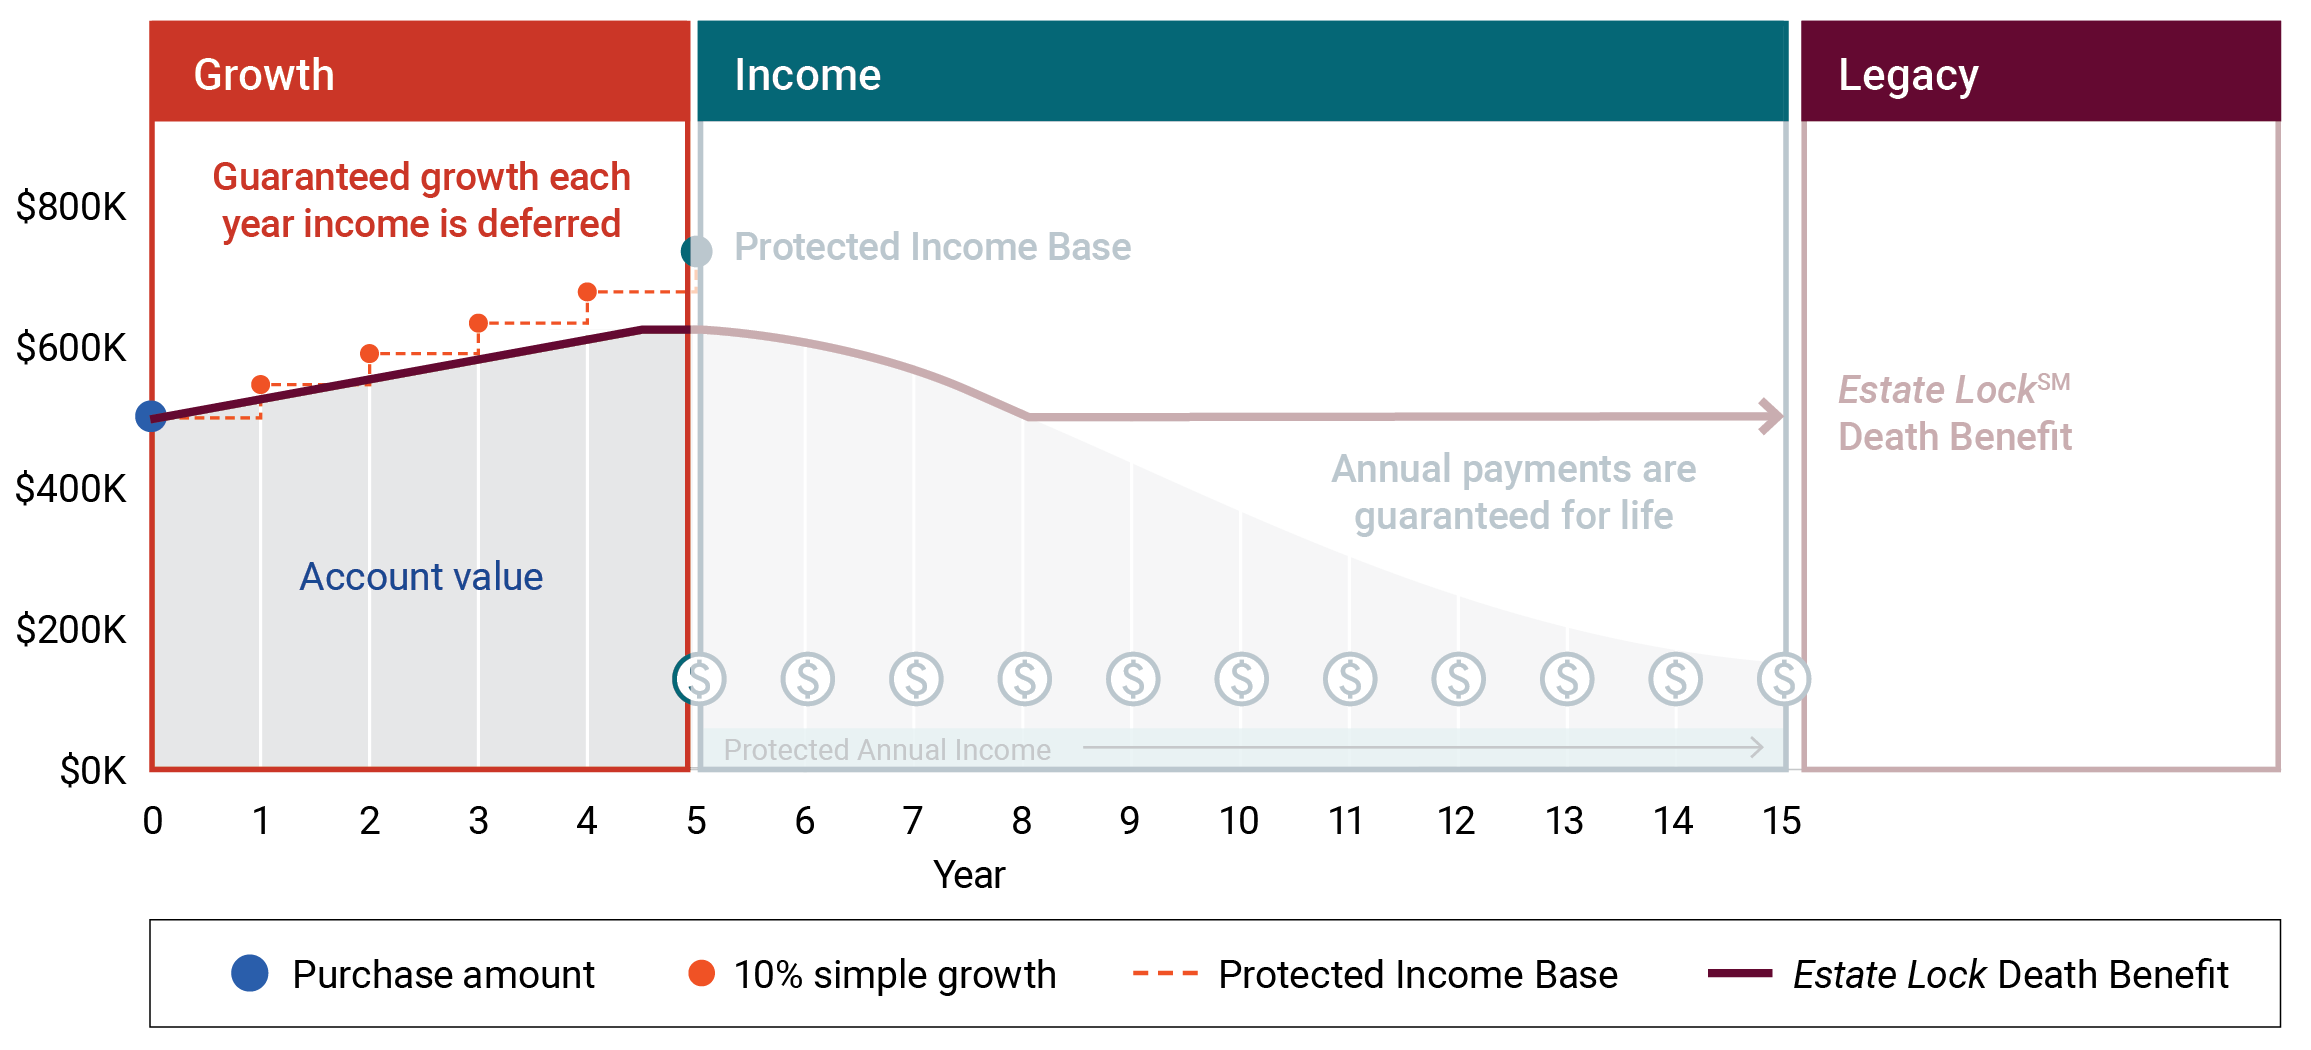
Sam, age 65, worked with his financial professional to allocate $500,000 to a fixed indexed annuity with Lincoln ProtectedPay Select and the Estate Lock Death Benefit. Since he’s not retiring right away, his Protected Income Base (the amount used to calculate his lifetime income) grows by 10% each year he waits to take income.
At the same time, his account value grew to over $600,000, based on the performance of the growth strategies he selected.
This chart is for illustrative purposes only. It does not reflect a specific allocation. Past performance does not guarantee future results. Guarantees are subject to the claims-paying ability of the issuer.
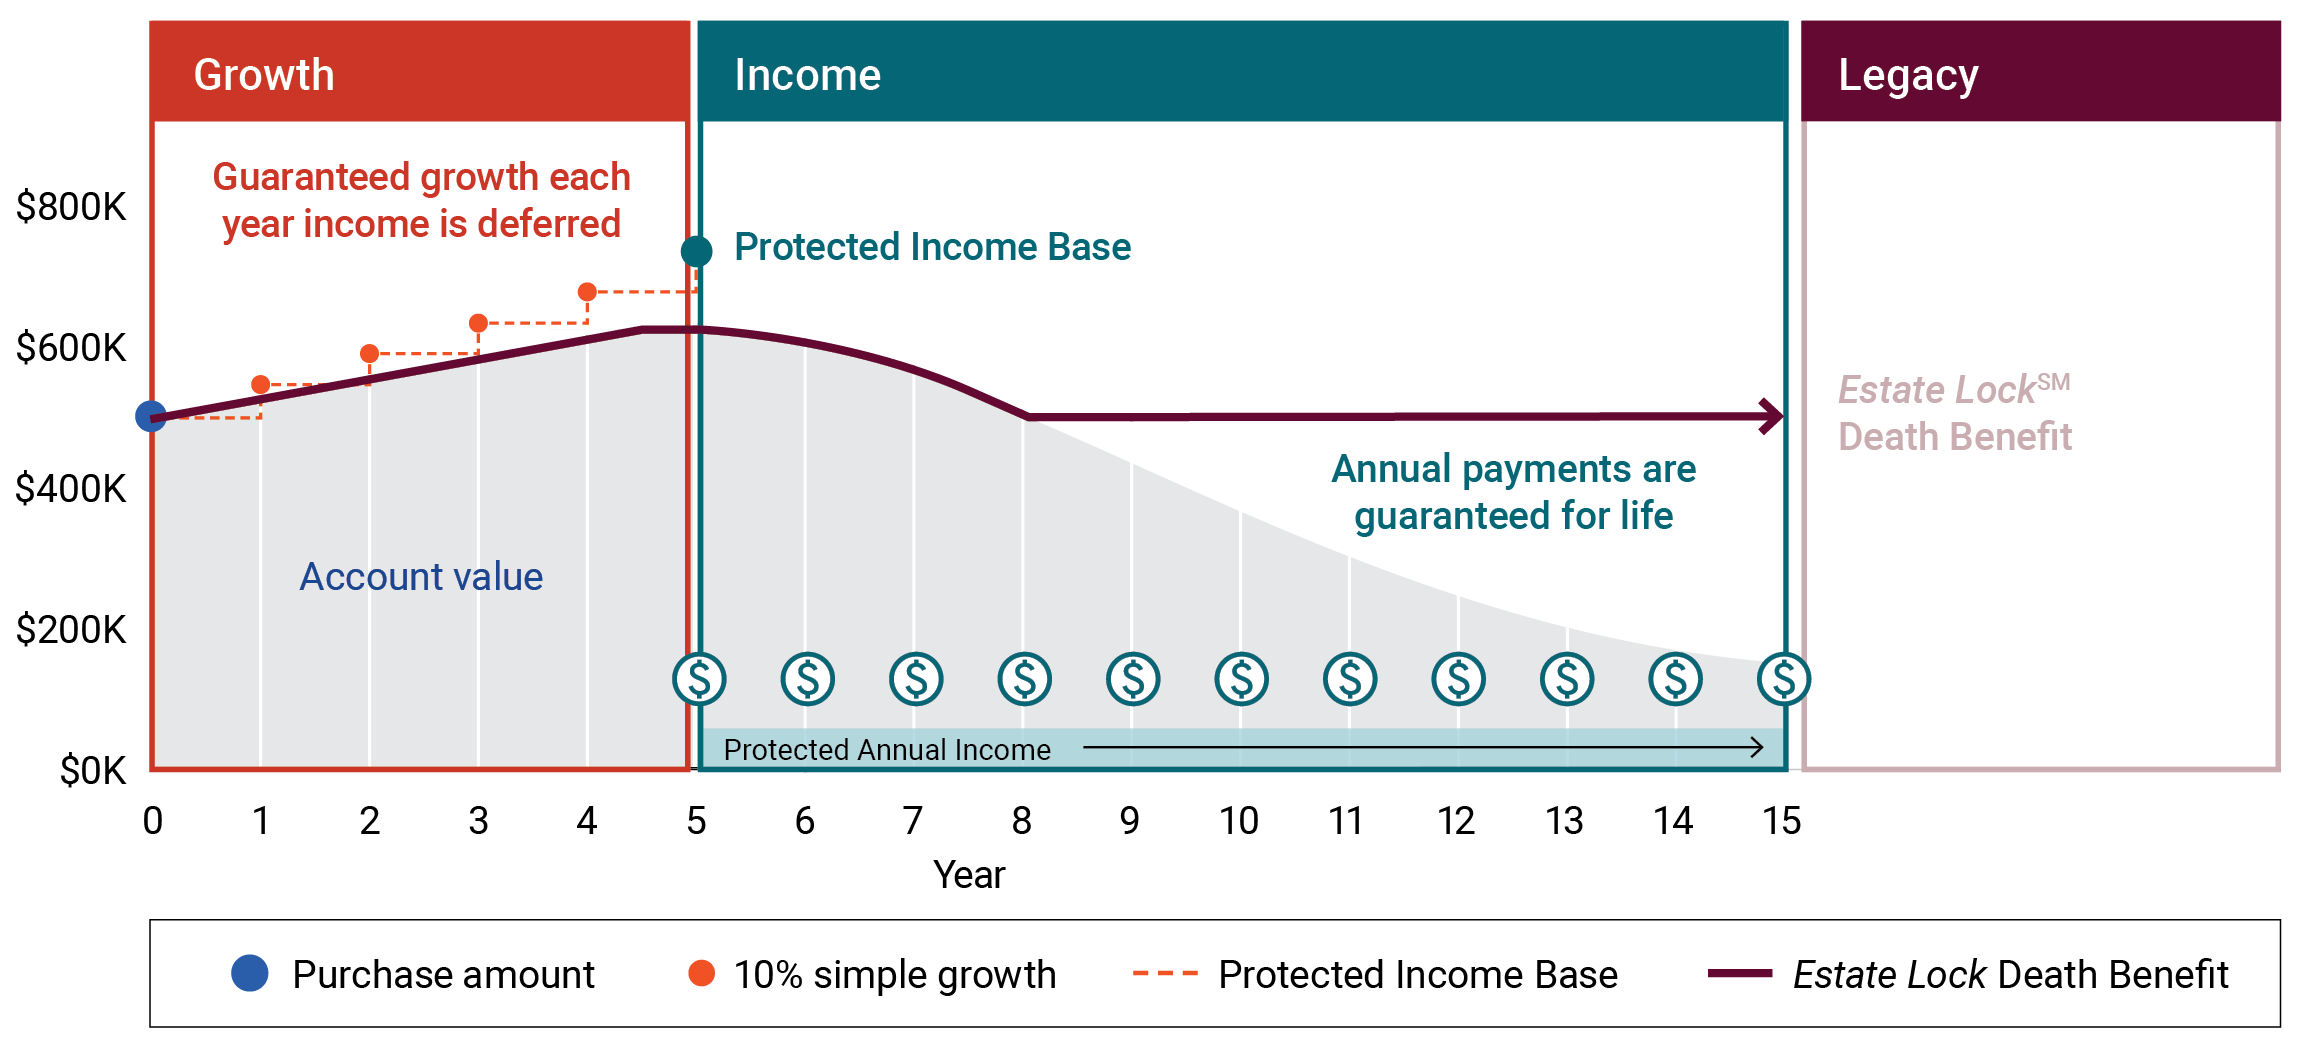
When Sam is ready to take income at age 70, his Protected Income Base has grown to $750,000. With a withdrawal rate of 6.10% based on his Protected Income Base, his Protected Annual Income payments will be $45,750 guaranteed for life.
This chart is for illustrative purposes only. It does not reflect a specific allocation. Past performance does not guarantee future results. Guarantees are subject to the claims-paying ability of the issuer.
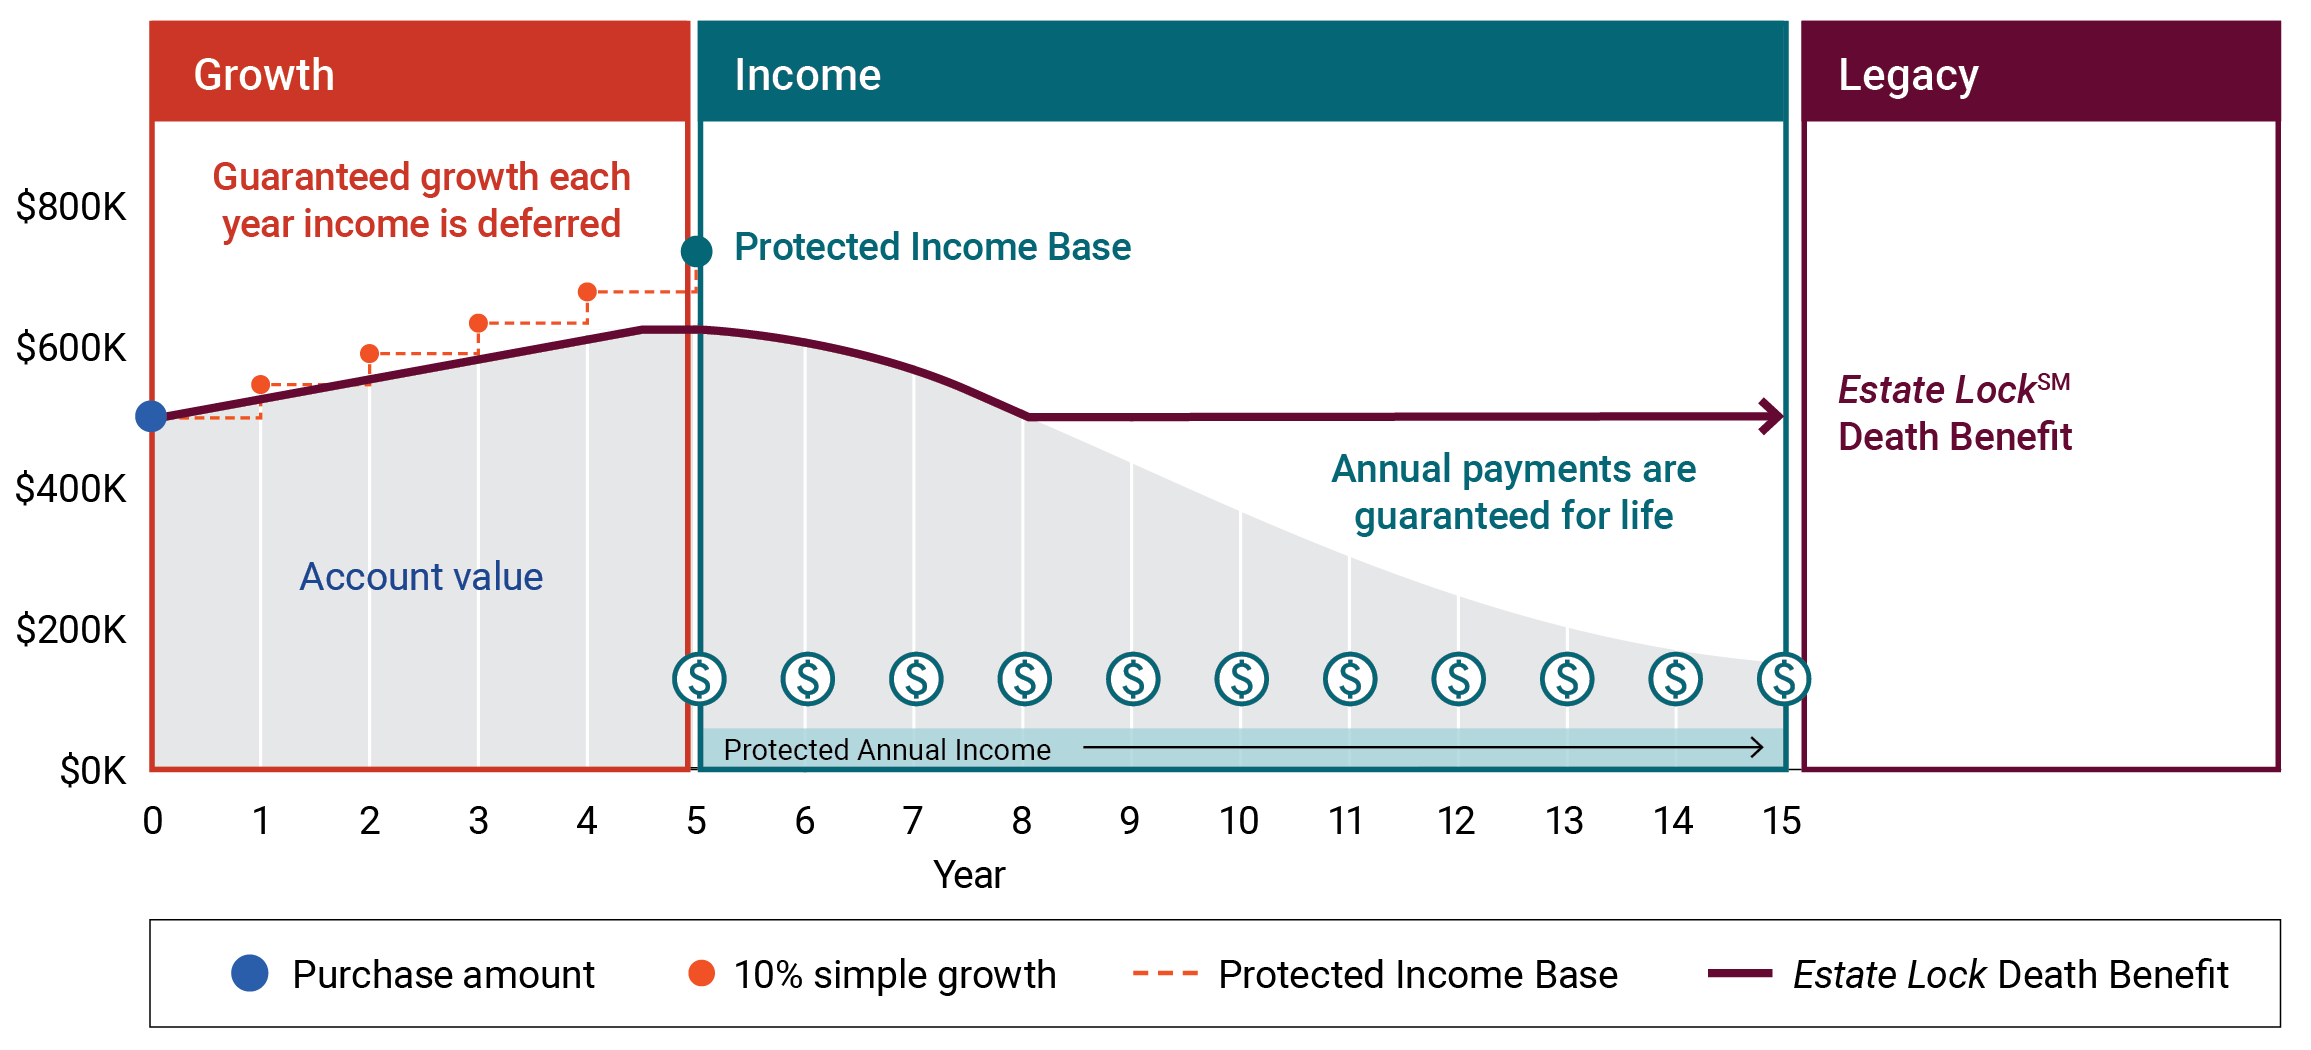
When Sam passed away ten years later, the Estate Lock Death Benefit allowed him to leave his full purchase amount of $500,000 to his daughter since his account value was greater than zero1 — even after taking $457,500 in income — bringing the total payout in this example to $957,500. He would have passed on the account value any year it was higher than $500,000.
This chart is for illustrative purposes only. It does not reflect a specific allocation. Past performance does not guarantee future results. Guarantees are subject to the claims-paying ability of the issuer.
Explore our fixed indexed annuity income products
The products below are subject to firm and state approvals:
Elevate your income plan
See the surprising results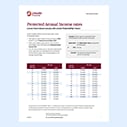
Lincoln ProtectedPay Select
See income rates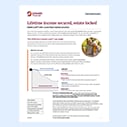
Estate Lock Death Benefit
Take a closer look1Lincoln ProtectedPay® Select is automatically included at issue for an annual cost of 1.10% single or joint (maximum annual charge is 2.25%).
2The 10% simple annual growth will continue for the earlier of 10 years or through age 85 (based on the oldest life for joint) and is not available in any year a withdrawal is taken. The Protected Income Base is not available as a separate benefit upon surrender, death or annuitization.
3In certain states, there is a cap for the Estate LockSM Death Benefit. The cap is equal to the greater of: (a) 125% of the contract’s cash surrender value, or (b) the lesser of the following two calculated amounts: i) premium(s), minus the sum of all withdrawals accumulated at an annualized interest rate of 10%; and ii) 250% of premium(s) minus the sum of all withdrawals. If your account value reaches $0, your income will continue for life but the Estate LockSM Death Benefit will terminate. Please refer to the product Disclosure Statement for a list of states where the cap applies.
Lincoln fixed indexed annuities (contract forms ICC1515-619, ICC17-622, ICC25-000702 and state variations) are issued by The Lincoln National Life Insurance Company, Fort Wayne, IN, and distributed by Lincoln Financial Distributors, Inc., a broker-dealer. The Lincoln National Life Insurance Company does not solicit business in the state of New York, nor is it authorized to do so. Contractual obligations are subject to the claims-paying ability of The Lincoln National Life Insurance Company.
Date last updated: 09/09/2026